
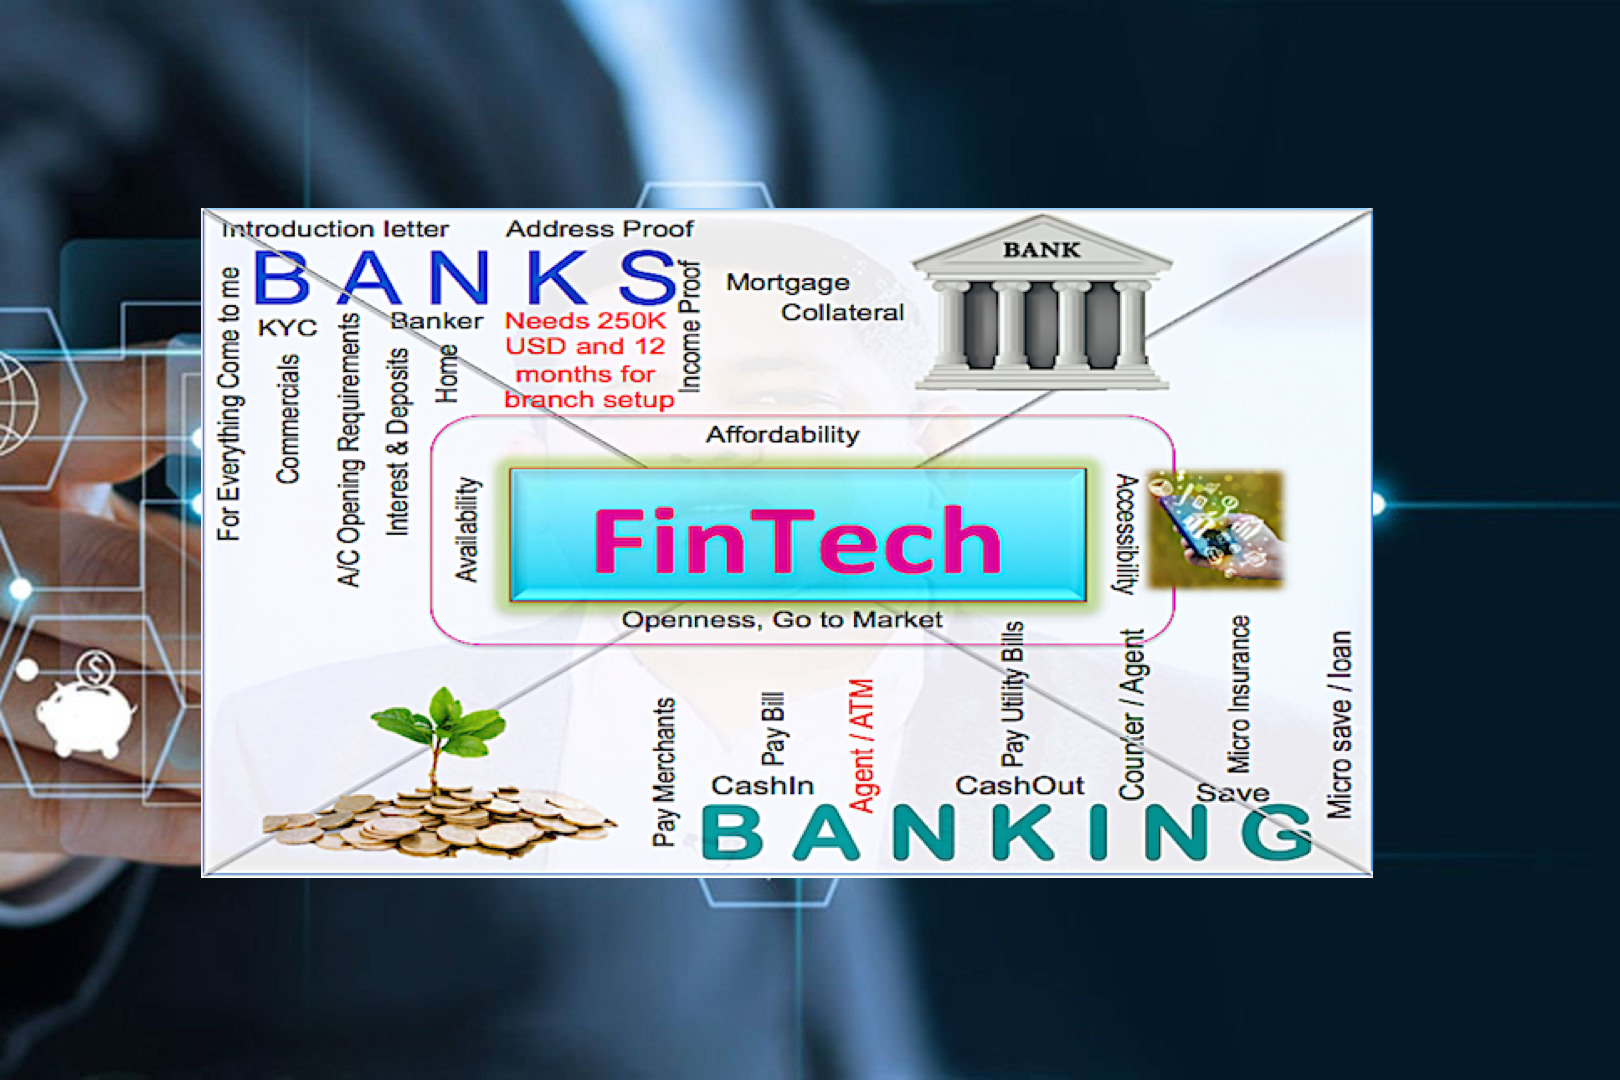
Banking or Banks – Banking, as we know it, has always been a pillar of financial stability. But let’s be honest—it’s no longer just about traditional banks. The rise of FinTech isn’t just a disruption; it’s a revolution. And like all revolutions, it’s forcing the old guard to adapt or fade into irrelevance.

For years, banks have held a monopoly over financial services, but FinTech startups are rewriting the rules. With lightning-fast innovation, seamless digital experiences, and a customer-first approach, FinTech is delivering what banks have struggled with for decades. Speed, convenience, and personalization.
This isn’t some distant future—it’s happening right now. FinTech in Africa, for example, isn’t just emerging; it’s thriving. Mobile money, digital wallets, and AI-driven lending platforms are already reshaping economies. In plain words, this isn’t the end of banking—it’s the end of banking as we knew it. I don’t claim to have all the answers, but based on my experience in the industry, one thing is clear: banking must evolve, or it will be left behind.
This article is a reflection of my own insights and observations, not a final conclusion. It was first published on Disruptive Views under “For Africa, Will FinTech Reign?”, where I explored the shifting dynamics of banking, financial services, and the unstoppable force of FinTech. The bottom line? FinTech isn’t here to destroy banking. It’s here to redefine it. And the smartest banks will be the ones that adapt, innovate, and collaborate—because in the future of finance, survival isn’t about size. It’s about agility.
– Happy New Year to all my readers –
Banks are stubborn because they’re old-school, risk-averse, and buried in regulations. They’ve been doing things the same way forever, and change feels like a giant headache. Plus, they know we still need them—so why rush to fix what (kind of) works?
Banking or Bank – Two are not coupled any more
Banks need to ditch their old-school mindset and start keeping up with what customers actually want—otherwise, they might not survive. Sure, banking as a concept isn’t going anywhere, but the traditional banks? They could be in trouble. From what I’ve seen, payments are evolving faster than ever. New methods pop up almost daily, and “payment intelligence” is helping us avoid chaos. Instead of chasing shiny new ideas, we’re using data to improve what already works. Test, measure, repeat—it’s not about stopping innovation, but about making it smarter.
Oh, and here’s the kicker: building new stuff on top of old, clunky systems rarely works. Sometimes, you’ve got to tear things down to find the hidden gems. That’s why I always say, “Let’s un-develop to innovate.” Sounds weird, but trust me, it works.

This is part 2 of my earlier post on December 26, 2014, “Will banks ever be successful in mobile money or mobile payments?” Artificial Intelligence has brought freshness to the financial services and payment service industries with the help of big data, which has just started growing. Currently, markets daily needs are shifting to more digital channels. Mobile wallets are one solution to this scenario.
Let’s talk about AI for a sec. Take facial recognition, for example—it’s a game-changer for customer experience. Seriously, it’s 10 to 15 times better at identifying people than we are. (Yeah, I know, it’s a little scary how good it is.)
What’s driving all this? Innovation, baby. Thanks to crazy-fast computing power and better connectivity, robotics and AI are growing faster than a TikTok trend. But here’s the thing: even though fintech disruptors have been pouring money into this stuff, it’s still just the beginning. Big banks and finance companies? They’re starting to wake up and smell the AI coffee. And trust me, once they fully jump in, things are going to get really interesting.
FinTech Provided Banking
You know what they say: more transactions mean more revenue. But let’s be real—what they’re really talking about is mining gold from the data collected behind the scenes. It’s all about turning numbers into dollars.
- Financial Inclusion vs. Fintech: Financial inclusion aims for accessibility and affordability, but fintech is playing a different game—focused on convenience, innovation, and customer-centric solutions.
- Banks vs. Fintech: Banks may be cheaper, but they’re falling behind due to outdated systems and lack of innovation. Fintech startups, on the other hand, are winning customers with creativity, convenience, and cutting-edge tech.
- Tech as a Game-Changer: Fintech relies on AI, data science, and software to disrupt traditional systems, creating advanced payment solutions that feel like a secret weapon for modern finance.
- The Real Goal: Financial inclusion must address affordability and accessibility, especially for those excluded due to remote locations, economic barriers, or rigid requirements like KYC and account fees.
That’s where AI, data science, and big data come in. They’re not just buzzwords—they’re tools to make finance fairer and more inclusive for everyone.
AILabPage – FinTech keeping artificial intelligence and data science at the foundation layer, where they belong, as partners to power up the whole thing. Rising to the highest level as the foremost leader in revolutionizing and pushing the boundaries in the field of electronic payments and financial inclusion
Welcome To The Realm Of FinTech
Here’s the thing: fintech has spent years tackling Africa’s biggest challenges—business, consumer needs, and tech gaps. They’re not just solving problems; they’re changing lives with innovative solutions that actually make sense. Meanwhile, banks are stuck in their old ways, with onboarding processes so restrictive they might as well be wearing blindfolds. They’ve missed the memo on adapting to a changing world, and it shows.
You know that old saying, “Opportunity knocks, but sometimes you have to build a door”? Well, let me put my own spin on it. Picture this:
| Scenario | What Happens | Outcome |
|---|---|---|
| 1 | Knock knock. Who’s there? FinTech. The bank, feeling lazy and suspicious, slams the door shut. | Classic move. Banks miss the opportunity, and fintech gets shut out. |
| 2 | Knock knock. Who’s there? FinTech, mobile networks, and a whole crew of innovators. This time, the door swings wide open, and they’re welcomed with open arms. | Fintech didn’t wait for banks—they built their own door. Now, fintech is owning the game while banks sweat. Banking survives, but banks? Not so much. |
Now, let’s talk mobile payments. The fintech market is about to explode, and mobile devices are the golden ticket. Whether it’s internet-based apps or good ol’ GSM networks, mobile is becoming the go-to gateway for financial services. And trust me, the possibilities are endless. We’re talking unlimited options, innovative solutions, and a future where your phone isn’t just a device—it’s your wallet, your bank, and your financial lifeline. So, while banks are busy guarding their gates, fintech is out here building bridges. And honestly? I’m here for it.
Banking from or Bank or From FinTech
Let’s get one thing straight: banking is essential, but banks? Not so much. The real threat to traditional banks isn’t some apocalyptic event—it’s fintech. These nimble, tech-savvy players are rewriting the rules, and if banks don’t wake up and smell the digital coffee, they’ll be left in the dust. To stay relevant, banks need to do three things: embrace change, partner with fintech innovators, and ditch their outdated playbook. Otherwise, they risk becoming relics while the idea of banking lives on without them.
Now, let’s talk mobile payments. It’s still early days, and no one’s declared a winner yet. This is like the first inning of a baseball game—anything can happen. We’ll have to wait and see how it plays out, but one thing’s for sure: there might be a stalemate, and not everyone’s going to come out on top. (Cue the dramatic music.)
- Digital is Survival, Not a Luxury – Banks must go digital to stay competitive, cutting costs, attracting customers, and boosting profits. But many bankers still feel it’s not enough—they need a strong digital value proposition that goes beyond transactions to genuinely improve customers’ lives.
- FinTech is Winning Customer Trust – Frustration with traditional banks is driving demand for fintech solutions, which offer faster, more customer-centric financial services.
- The Perfect Storm for FinTech Growth – With low interest rates and abundant capital, fintech startups are thriving, fueled by a wave of financial professionals eager to disrupt the status quo.
So, here’s the bottom line: banks have a choice. They can either adapt and thrive, or cling to the past and fade away. The future of banking isn’t about brick-and-mortar branches or dusty old ledgers—it’s about agility, innovation, and putting the customer first. And if banks don’t get that? Well, fintech will be more than happy to take their place.
Pain or Cost – Will go with little Cost
Let’s talk convenience. When it comes to mobile financial services (MFS) or fintech, it’s all about how easy it is to use their platforms, send money, and cash out. The bigger their network, the happier their users. And fintech? Oh, they’re playing this like a pro—acting like the “god of convenience” while subscribers pray for the perfect balance. Meanwhile, banks that actually innovate? They’re less likely to need outside help. But let’s be real, not all banks are there yet.
Here’s the thing: fintech isn’t just doing its job—it’s crushing it. And get this—they’re even teaming up with their so-called competition. Because let’s face it, no one can do this alone. Banks, fintech, telcos—they all need each other to scale up and build real, lasting relationships with different customer segments. Collaboration isn’t just nice; it’s essential.
And then there’s the magic of cross-industry partnerships. These alliances let companies offer financial and non-financial products they couldn’t pull off solo. Think of it like a potluck dinner—everyone brings something to the table, and suddenly, you’ve got a feast. So, here comes fintech, strutting in like the guest of honor. Let’s give it a warm welcome, shall we?
Now, let’s rewind a bit. The fintech industry really came alive in 2015, and it’s been riding that wave of confidence ever since. But back in 2012? Not so much. I remember people saying, “Why bother? The banks have a monopoly, and no one’s built a successful payments company since PayPal and those plastic money guys.” Oh, how times have changed.
Financial Services Intelligence – Payment Intelligence
MaRS’ Financial Technology (FinTech) Cluster connects the financial services sector with startups developing next-generation technology in emerging payments, financial services, peer-to-peer transactions, alternative lending, and crypto-currencies. Fintech startups have the most comprehensive set of resources across the world, and their vision is soothing to the world and people’s lives, giving them another reason to live long and grow in folds. Killing everything that comes in the way of innovation.
- FinTech’s Power Play—Speed, Access & Opportunity – Armed with the right partners, tech, and talent, FinTech founders aren’t just building products—they’re fast-tracking success. Early validation, investor backing, customer feedback, and real-world sales channels aren’t distant dreams; they’re table stakes in this ecosystem.
- From Fortress Banks to FinTech Frenzy – Finance was once an impenetrable fortress, guarded by towering banks and layers of regulation. Disruption was rare—unless you count global financial meltdowns. Today? It’s an entrepreneur’s playground, with FinTech rewriting the rules and reshaping financial services at breakneck speed.
- The Ultimate Mic Drop—Banking vs. Mobile Money – Banks made opening an account a privilege, demanding hefty deposits just to get started. Meanwhile, mobile money lets anyone with a few cents and a SIM card dive into financial services instantly. The message was clear: accessibility wins and FinTech got the memo first.
FinTech companies often face doubts from financial regulators along with tough competition from established players. The online financial sector is also an increasing target of distributed denial-of-service extortion attacks. This security challenge is also faced by historical bank companies since they do offer Internet-connected customer services.
Why Welcome FinTech
FinTech isn’t just growing—it’s exploding. Sure, there are hurdles, bottlenecks (both natural and industry-made), and the occasional regulatory headache, but let’s be real: nothing is slowing this beast down. Everywhere you look, FinTech startups are rewriting the rules. Need to send money to a friend? Done in seconds. Paying for coffee? Just tap, scan, or swipe. From mobile apps to USSD, NFC, and QR codes, these companies are making money move faster than ever. And lending? That’s taking off too—because why should getting a loan feel like applying for a government security clearance?
Investors are all in. Billions of dollars have poured into FinTech in just the past year. If that’s not a sign of confidence, I don’t know what is. The message is clear: the future of finance isn’t coming—it’s already here.
| Key Insight | Deep Tech & Business Angle | The Bigger Picture |
|---|---|---|
| FinTech & Insurance – A Goldmine | Startups are disrupting insurance, and even industry giants are paying attention. Despite its size, insurance remains one of the costliest areas in financial services. | The inefficiencies in insurance create room for FinTech innovation, making coverage more accessible and cost-effective. |
| Banks vs. Telcos – The Compliance Dilemma | Banks are tied down by regulations, while telcos move with agility. Until banks rethink compliance to match market needs, they’ll struggle to compete with FinTech. | Regulation is both a shield and a shackle—balancing risk management with innovation is the real challenge. |
| Marketing – The FinTech Achilles’ Heel | FinTechs are revolutionizing finance but struggle with marketing. Legacy giants outspend them, making visibility a major hurdle. | Without strong branding, even the best FinTech solutions risk fading into obscurity. |
| Financial Inclusion – The FinTech Promise | FinTech is breaking barriers, offering financial services to underserved communities at fair prices—something traditional banks failed to do. | The future of finance lies in accessibility, not exclusivity. FinTech is bridging the gap. |
| MSMEs & Digital Banking – A New Playbook | Banks are shifting from passive financial services to active engagement, offering digital tools that empower MSMEs. | The game has changed—banks need to be partners in business growth, not just transaction processors. |
| Speed Matters – Frictionless Access | Registration should be seamless, and credit assessments should happen in minutes, not days. Efficiency is the new currency. | FinTech thrives on convenience—delays are a dealbreaker in the digital age. |
| Can Banking Exist Without Banks? | The answer is unfolding before our eyes—FinTech is decentralizing finance, pulling services out of banks and into digital ecosystems. | The real question isn’t if banking can exist without banks, but how fast this shift will happen. |
| Banks & FinTech – A Love-Hate Relationship | Banks are partnering with FinTechs, but is it out of true belief in innovation or just survival instinct? | Collaboration or competition? The line between banks and FinTech is getting blurrier by the day. |
Speaking of fintech, remember when Apple Pay first hit the scene? There was this whole drama about how Apple basically shrugged off what banks had to say. I remember hearing from someone in the payments space—maybe a research manager or an innovator—who pointed out how Apple just did its own thing. And honestly, it worked. But it makes you wonder: what’s in it for the banks? Why would they want to play ball with a tech giant that doesn’t exactly play by their rules?

Conclusion – The FinTech sector encounters challenges in persuading regulators and frequently experiences substantial regulatory setbacks, as there is no government agency specifically dedicated to supporting them. The protection of private financial information belonging to consumers and corporations is a significant concern for regulatory bodies due to the possibility of security breaches and cyberattacks.
—
Points to Note:
All credits, if any, remain with the original contributor only. We have covered all the basics around mobile payment security and the importance of mobile payment data. In the next upcoming post, we will talk about implementation, usage, and practice experience for markets.
Books + Other readings Referred
- Research through the open internet, news portals, white papers, notes made at knowledge sharing sessions, and live conferences and lectures
- Lab and hands-on experience of @AILabPage (Self-taught learners group) members.
Feedback & Further Question
Do you have any questions about AI, machine learning, data billing and charging, data science, or big data analytics? Leave a question in the comment section or ask via email. I will try my best to answer it.
====================== About the Author =================================
Read about Author at: About Me
Thank you all, for spending your time reading this post. Please share your feedback / comments / critics / agreements or disagreement. Remark for more details about posts, subjects and relevance please read the disclaimer.
FacebookPage Twitter ContactMe LinkedinPage =========================================================================

Very Nice Article sir. Great job!!
[…] Remember my old post : Banking and Banks are no longer married !! […]
[…] The verdict? One system gatekeeps; the other gate-opens. Remember my 2016 blog rant (“Banking is needed not the Banks”)? Nothing’s changed. Banks still move at the speed of fax machines while fintechs build […]